How to Compare College Net Price Before You Apply
Learn how to compare college net price using cost of attendance, grants, calculators, and official financial aid information.
If you are comparing colleges by tuition alone, you may be sorting schools by the least useful number. A college with a higher published price can sometimes offer more grants, while a lower-cost school can still leave your family with a larger bill after aid.
The number to compare before you apply is your estimated net price: the expected cost after grants and scholarships are subtracted from the college's cost of attendance. It is an estimate, not a promise, but it gives you a better starting point for building an affordable list.
Know Which Price You Are Looking At
College cost conversations often mix together several different numbers:
- Tuition and fees: the charges for enrolling and taking classes. This is only one part of the yearly cost.
- Cost of attendance: the school's estimate of tuition, fees, housing, food, books, supplies, transportation, and other education-related expenses for an academic year. Federal Student Aid explains that the amount and included items can differ from one school to another.
- Net price: an estimate of what a student pays after grants and scholarships are subtracted from the cost of attendance. Grants and scholarships generally do not have to be repaid.
- Your final out-of-pocket cost: the amount you determine from a specific financial aid offer, including which aid is free, which aid must be earned or repaid, and which expenses are not covered.
The Federal Student Aid glossary defines net price as an estimate of yearly out-of-pocket cost. The Department of Education's Net Price Calculator Center says college calculators use information about you to estimate what similar students paid after grants and scholarship aid.
Start With a Consistent Comparison
Before opening a calculator, make a simple table for every college you are considering. Use the same columns for each school:
| School | Cost of attendance | Grants and scholarships | Estimated net price | Questions to verify |
|---|---|---|---|---|
| College A | ||||
| College B |
Do not compare one school's tuition with another school's full cost of attendance. That makes the difference look smaller or larger for reasons unrelated to affordability. Keep the time period consistent too: compare annual estimates with annual estimates, and check whether housing and food are included.
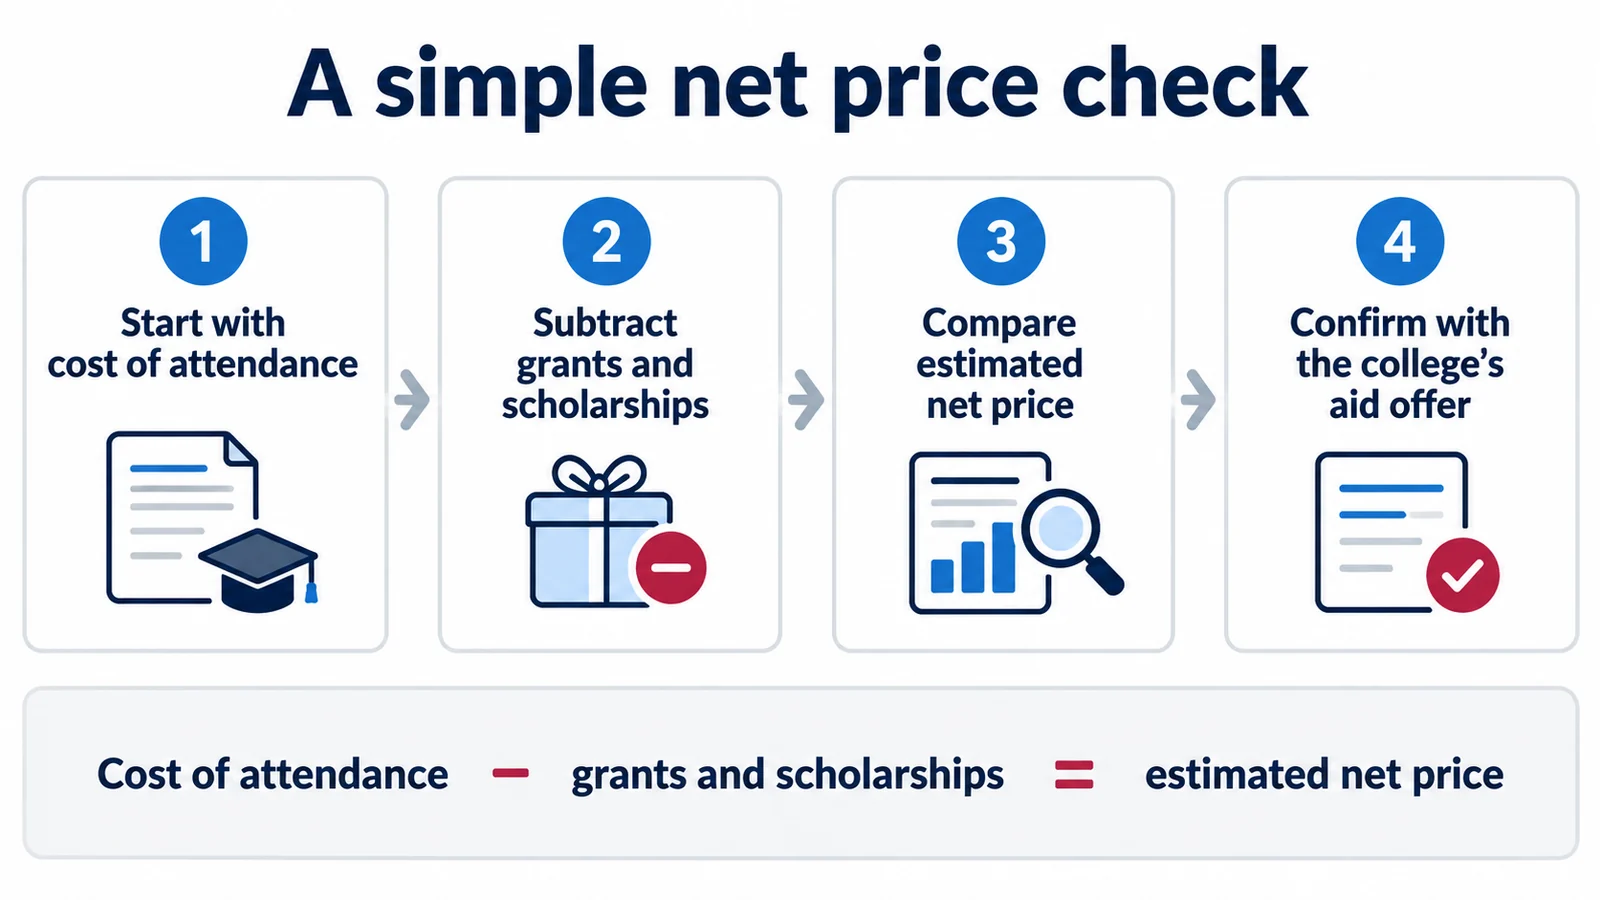
The basic calculation is:
Cost of attendance − grants and scholarships = estimated net price
If a calculator reports a net price directly, record the inputs and assumptions beside the result. A number without context is hard to revisit later.
Use Three Official Sources Together
No single source answers every affordability question. Use each one for the job it does best.
1. College Scorecard for a comparable starting point
The U.S. Department of Education's College Scorecard provides standardized information about colleges, including costs and net price estimates. Federal Student Aid notes that Scorecard can show average annual cost and net price broken down by family income, along with other measures such as graduation and borrowing information.
Use it to spot patterns across several schools and to decide which colleges deserve a closer look. Remember that an average is not your personal estimate. It may reflect different students, years, residency situations, and aid circumstances than yours.
2. Net Price Calculator Center to find each college's calculator
The Net Price Calculator Center links to calculators on college websites. Enter information as carefully as you can, but treat the result as a planning estimate. If your family situation is unusual, income has changed, or you expect to live somewhere different from the assumed housing arrangement, write that down as a question for the financial aid office.
Save the date of each estimate. Calculator results can be based on prior-year information, and colleges may update their tools or assumptions.
3. The college's own financial aid pages for details
Visit each college's official financial aid site to check how it describes grants, scholarships, housing, meal plans, work-study, loans, and renewal requirements. Look for conditions that can change your cost after the first year, such as a scholarship requiring a particular GPA or housing cost that is not included in the estimate.
Ask Whether the Estimate Fits Your Situation
Two students can receive different net prices at the same college. Before treating an estimate as a decision, ask:
- Did I enter the correct dependency, residency, household, and enrollment information?
- Does the estimate include housing and food, or only direct charges to the college?
- Are the grants need-based, merit-based, or a mixture of both?
- Is a scholarship renewable, and what must I do to keep it?
- Is work-study included as aid I must earn rather than money guaranteed up front?
- Does the college expect a student contribution, parent contribution, or outside scholarship?
- Are travel, health insurance, supplies, deposits, and personal expenses missing from the estimate?
These questions do not make a calculator useless. They help you understand what the number means and what could make your real cost different.
Compare Affordability With Fit
The lowest estimated net price should not automatically win. A college still needs to offer the major, learning environment, location, support, and academic path you need. A cheaper option that does not fit your goals may create new costs in time, travel, or transferring.
Use a two-part decision guide:
- Affordability screen: Is the estimated net price within a range your family can realistically discuss? What part might require savings, work, or borrowing?
- Fit screen: Does the college meet your academic and personal priorities, and can you explain why it belongs on your list?
Tools such as UniMatch can help you compare colleges by major, location, cost, and fit. Use that comparison to organize questions and narrow research, not to replace the college's official information.
Recheck After You Receive Aid Offers
Before committing, use the actual aid offers as your source of truth. Federal Student Aid recommends comparing total expected costs with grants, scholarships, state aid, institutional aid, work-study, and loans. A loan can reduce the amount due now while increasing what you repay later, so keep borrowed money separate from grants and scholarships in your table.
For each offer, calculate:
- Cost of attendance and additional expenses
- Minus grants and scholarships that do not need to be repaid
- Equals the remaining estimated bill
- Then list work-study and loans separately, with any conditions or fees
If an offer is unclear, contact the financial aid office and ask for a line-by-line explanation. Do not assume two colleges use the same labels or include the same expenses.
A Net Price Checklist Before You Apply
Use this checklist for every serious option:
- Find the school's cost of attendance for the year you would enter.
- Record whether housing, food, books, travel, and other expenses are included.
- Check the College Scorecard for comparable cost and net price context.
- Complete the college's official net price calculator.
- Save the estimate, date, assumptions, and questions.
- Separate grants and scholarships from work-study and loans.
- Check scholarship renewal rules and likely changes after the first year.
- Compare the result with your family's realistic budget and the college's academic fit.
Comparing net price before you apply will not predict your final aid offer perfectly. It will give you a clearer set of questions, reduce surprises, and help you build a college list around both fit and a cost your family can discuss honestly. Start with two or three schools, use the same comparison table, and update it whenever you learn something new.